


Results for the full year to 31 March 2024

Allison Kirkby, Chief Executive, commenting on the results, said “BT Group built and connected customers to our next generation networks at record speed and efficiency over the past year, while continuing to grow revenue and EBITDA. Having passed peak capex on our full fibre broadband rollout and achieved our £3 billion cost and service transformation programme a year ahead of schedule, we’ve now reached the inflection point on our long-term strategy. “This delivery and greater capex efficiency gives us the confidence to provide new guidance for significantly increased short term cash flow and sets out a path to more than double our normalised free cash flow over the next five years. This enhanced cash flow allows us to increase our dividend for FY24 by 3.9% to 8.0 pence per share. We’re also setting a further £3bn of gross annualised cost savings to be reached by the end of FY29. "As we move into the next phase of BT Group's transformation, we are sharpening our focus to be better for our customers and the country, by accelerating the modernisation of our operations, and by exploring options to optimise our global business. This will create a simpler BT Group, fully focused on connecting the UK, and well positioned to generate significant growth for all our stakeholders.” |
Continued strong delivery against our strategy
- FTTP build rate accelerated to 1.0m premises passed in the quarter, a record 78k per week. FTTP footprint now over 14m premises with a further 6m where initial build is underway; on track to reach 25m by December 2026. Department for Science, Innovation and Technology has notified Openreach of its preferred bidder status for Project Gigabit cross-regional supplier contract (Type C)1
- Strong Openreach customer demand for FTTP with net adds of 397k in Q4; total premises connected now over 4.8m with increased take-up rate of 34%
- Openreach broadband ARPU in FY24 grew year-on-year by 10% to £15.1 due to price rises and increased volumes and mix of FTTP; Openreach broadband line losses of 491k, a 2% decline in the broadband base, as weaker than expected growth in the broadband market in FY24 did not offset competitor losses which were at comparable levels to FY23; we expect that the broadband market will recover over the medium term but if it remains weak over the next 12 months then we can expect Openreach’s broadband base to be impacted by moderately higher competitor losses
- Consumer broadband ARPU in FY24 increased 5% year-on-year to £41.2; Consumer postpaid mobile ARPU increased 9% year-on-year to £19.4; monthly churn for the year remained stable in a competitive market with broadband and postpaid mobile both at 1.1%
- Business financial performance continues to be impacted by higher input costs, legacy declines, a one off revenue adjustment and prior year one-offs, partly offset by cost transformation and growth in Small & Medium Business (SMB) and Security
- Retail FTTP base grew year-on-year by 40% to 2.6m of which Consumer 2.4m and Business 0.2m; 5G base 11.1m, up 29% year-on-year
- Cost transformation target of £3bn gross annualised cost savings since May 2020 achieved 12 months early, at a cost to achieve of £1.5bn, £0.1bn lower than target. Announced further £3bn gross annualised cost savings by end FY29 at a cost to achieve of £1.0bn
- BT Group NPS of 24.0, up 1.0pts year-on-year, further improving customer experience
- Looking forward, BT Group will focus on the UK; we will explore all options to optimise our global business
FY24 Normalised free cash flow2 (NFCF) ahead of guidance; dividend raised; growth in NFCF to £1.5bn in FY25, £2.0bn in FY27 and £3bn by the end of the decade
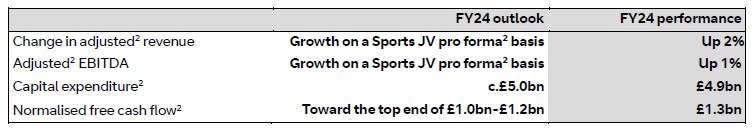
- Reported revenue £20.8bn, up 1%; adjusted2 revenue £20.8bn, up 2% on a pro forma3 basis due to price increases and fibre-enabled product sales in Openreach, increased service revenue in Consumer with annual contractual price rises being aided by higher roaming and increased FTTP connections, partly offset by legacy product declines and a one-off revenue adjustment in Business
- Adjusted2 EBITDA £8.1bn, up 2%; and up 1% on a pro forma3 basis with revenue flow through and cost control more than offsetting cost inflation and one-off items; Openreach and Consumer delivered strong EBITDA growth, partially offset by EBITDA decline in Business due to increased input costs and legacy high-margin managed contract declines
- We have recognised a non-cash impairment of goodwill allocated to Business of £488m as a specific item, reflecting a decline in profitability in recent years
- Reported profit before tax £1.2bn, down 31% primarily due to impairment of goodwill, increased depreciation, amortisation and pension interest expense, partially offset by adjusted2 EBITDA growth
- Capital expenditure ('capex') £4.9bn, down 3% primarily driven by lower networks spend despite higher FTTP build in the year due to reduced unit costs and efficiencies; cash capex of £5.0bn also down 6%
- Net cash inflow from operating activities £6.0bn; normalised free cash flow2 £1.3bn, down 4% due to working capital timing and a prior year tax refund, partly offset by EBITDA growth and lower capital expenditure
- Net debt £19.5bn (FY23: £18.9bn), increased mainly due to our scheduled pension scheme contributions of £0.8bn
- Gross IAS 19 pension deficit of £4.8bn, up from £3.1bn at 31 March 2023 mainly due to the increase in real interest rates and narrowing of credit spreads over the period, partly offset by our scheduled contributions
- Final dividend of 5.69 pence per share (pps), bringing the full year dividend to 8.00pps, up 3.9%
- FY25 Outlook: Adjusted2 revenue growth of 0-1% and EBITDA of around £8.2bn; capital expenditure excluding spectrum less than £4.8bn; normalised free cash flow of around £1.5bn
- Mid-term guidance: Consistent and predictable adjusted2 revenue growth and EBITDA growth ahead of revenue, enhanced by cost transformation from FY26 to FY30; capital expenditure excluding spectrum less than £4.8bn until FY26, reducing by c. £1bn post peak FTTP build; normalised free cash flow of c. £2.0bn in FY27 and c. £3.0bn by the end of the decade

Customer-facing unit updates

Performance against FY24 outlook
1 Subject to contract signing.
2 See Glossary.
3 See 'Prior period comparatives' section below for more information on pro forma and re-presented measures.
n/m: comparison not meaningful
Prior period comparatives
Throughout this release, comparative financial information for year to 31 March 2023 ('FY23') has been re-presented to reflect the merger of our Global and Enterprise business units to form Business; and the change in the methodology used to allocate shared Network, Digital and support function costs across our units, which improves the relevance of our financial reporting by better allocating internal costs to the drivers behind those costs. These adjustments are made pursuant to IFRS accounting requirements, for more information see note 1 to the condensed consolidated financial statements on page 17 .
In addition, the group and operating review sections of this release present comparative financial information for the Consumer customer-facing unit and BT Group overall on an unaudited 'pro forma' basis. This reflects adjustments that estimate the impact as if trading in relation to BT Sport has been equity accounted in FY23, akin to the Sports JV being in place historically. Analysis on a pro forma basis enables comparison of results on a like-for-like basis.
The Additional Information on page 29 presents a bridge between financial information for the year to 31 March 2023 as published on 3 November 2022, and the comparatives presented in this release. For further information see https://bt.com/about for separate publications covering the formation of Business and cost allocation changes, (published 27 June 2023), and the pro forma adjustments (published 18 October 2022).
Glossary
| Adjusted | Adjusted measures (including adjusted revenue, adjusted operating costs, adjusted operating profit, and adjusted basic earnings per share) are before specific items. Adjusted results are consistent with the way that financial performance is measured by management and assist in providing an additional analysis of the reporting trading results of the group. |
| Adjusted EBITDA | Earnings before interest, tax, depreciation and amortisation, before specific items, share of post tax profits/losses of associates and joint ventures and net finance expense. |
| Free cash flow | Net cash inflow from operating activities after net capital expenditure. |
| Capital expenditure | Additions to property, plant and equipment and intangible assets in the period. |
| Normalised free cash flow | Free cash flow (net cash inflow from operating activities after net capital expenditure) after net interest paid, payment of lease liabilities, net cash flows from the sale of cash flows related to contract assets, monies received as prepayment for the sale of redundant copper, dividends received from non-current assets investments, associates and joint ventures, and net purchase or disposal of non-current asset investments, before pension deficit payments (including their cash tax benefit), payments relating to spectrum, and specific items. It excludes cash flows that are determined at a corporate level independently of ongoing trading operations such as dividends paid, share buybacks, acquisitions and disposals, repayment and raising of debt, cash flows relating to loans with joint ventures, and cash flows relating to the Building Digital UK demand deposit account which have already been accounted for within normalised free cash flow. For non-tax related items the adjustments are made on a pre-tax basis. |
| Net debt | Loans and other borrowings and lease liabilities (both current and non-current), less current asset investments and cash and cash equivalents, including items which have been classified as held for sale on the balance sheet. Amounts due to joint ventures, loans and borrowings recognised in relation to monies received from the sale of cash flows of contract assets and as prepayment for the forward sale of redundant copper are excluded. Currency denominated balances within net debt are translated into sterling at swapped rates where hedged. Fair value adjustments and accrued interest applied to reflect the effective interest method are removed. |
| Service revenue | Earned from services delivered using our fixed and mobile network connectivity, including but not limited to, broadband, calls, line rental, TV, residential sport subscriptions, mobile data connectivity, incoming & outgoing mobile calls and roaming by customers of overseas networks. |
| Re-presented | FY23 comparatives throughout this release have been re-presented to reflect: (i) the merger of our Global and Enterprise business units to form Business; and (ii) the change in our methodology used to allocate shared Network, Digital and support function costs across our units. Refer to the 'Prior period comparatives' section on page 3 and note 1 to the condensed consolidated financial statements on page 17 for more details, and to Additional Information on page 29 for a bridge between previously published FY23 financial information and re-presented numbers. |
| Pro forma | Unaudited pro forma results estimate the impact on the group as if trading in relation to BT Sport has been equity accounted in FY23, akin to the Sports JV being in place historically. Refer to the 'Prior period comparatives' section on page 3 for more information and to Additional Information on page 29 for a bridge between previously published financial information (re-presented as noted above) and pro forma numbers. |
| Specific items | Items that in management’s judgement need to be disclosed separately by virtue of their size, nature or incidence. In the current period these relate to changes to goodwill impairment, our assessment of our provision for historic regulatory matters, restructuring charges, historical property-related provisions, divestment-related items and net interest expense on pensions. In determining whether an event or transaction is specific, management considers quantitative as well as qualitative factors such as the frequency or predictability of occurrence. |
We assess the performance of the group using a variety of alternative performance measures. Reconciliations from the most directly comparable IFRS measures are in Additional Information on pages 29 to 31.
Forward-looking statements – caution advised
Certain information included in this announcement is forward looking and involves risks, assumptions and uncertainties that could cause actual results to differ materially from those expressed or implied by forward looking statements. Forward looking statements cover all matters which are not historical facts and include, without limitation, projections relating to results of operations and financial conditions and the Company’s plans and objectives for future operations. Forward looking statements can be identified by the use of forward looking terminology, including terms such as ‘believes’, ‘estimates’, ‘anticipates’, ‘expects’, ‘forecasts’, ‘intends’, ‘plans’, ‘projects’, ‘goal’, ‘target’, ‘aim’, ‘may’, ‘will’, ‘would’, ‘could’ or ‘should’ or, in each case, their negative or other variations or comparable terminology. Forward looking statements in this announcement are not guarantees of future performance. All forward looking statements in this announcement are based upon information known to the Company on the date of this announcement. Accordingly, no assurance can be given that any particular expectation will be met and readers are cautioned not to place undue reliance on forward looking statements, which speak only at their respective dates. Additionally, forward looking statements regarding past trends or activities should not be taken as a representation that such trends or activities will continue in the future. Other than in accordance with its legal or regulatory obligations (including under the UK Listing Rules and the Disclosure Guidance and Transparency Rules of the Financial Conduct Authority), the Company undertakes no obligation to publicly update or revise any forward looking statement, whether as a result of new information, future events or otherwise. Nothing in this announcement shall exclude any liability under applicable laws that cannot be excluded in accordance with such laws.

Download PDF - Results for the full year to 31 March 2024
BT Group is the UK’s leading provider of fixed and mobile telecommunications and related secure digital products, solutions and services. We also provide managed telecommunications, security and network & IT infrastructure services to customers across 180 countries.
BT Group consists of three customer-facing units: Consumer serves individuals and families in the UK; Business covers companies and public services in the UK and internationally; Openreach is an independently governed, wholly owned subsidiary wholesaling fixed access infrastructure services to its customers - over 700 communications providers across the UK.
British Telecommunications plc is a wholly owned subsidiary of BT Group plc and encompasses virtually all businesses and assets of the BT Group. BT Group plc is listed on the London Stock Exchange.
For more information, visit www.bt.com/about


